Office Info
Oakwyn Realty
101 - 3151 Woodbine Drive North Vancouver, BC V7R 2S4
Stay Connected
First-time buyers in North Vancouver
Yes, it can be done. It just takes a plan, and knowing every program you qualify for.
First-time buyers in BC have more help than most people realize. There is a tax-free savings account, an RRSP withdrawal, a Property Transfer Tax exemption, a GST rebate on new homes and a 30-year mortgage option. Used together, they can change what you can afford.
Tell us where you are at, and we will put it all on one page: what you can likely afford, which programs apply to you, and the neighbourhoods worth a look first. No cost and no pressure.
How it works
Three steps. You can stop at any point.
01
Today, about two minutes
Your rough budget, your timing, and the kind of home and area you have in mind. Not sure yet? That is fine too.
02
Within 1 business day
The programs you likely qualify for, a realistic price range, your estimated closing costs, and two or three neighbourhoods that fit your budget and life.
03
When you are ready
By phone, video or over coffee. We will set up a search that sends you new listings as they hit the market.
Your first-home plan
Name and email are all we need. Add a phone number if you would rather talk.
Oakwyn Realty
101 - 3151 Woodbine Drive North Vancouver, BC V7R 2S4
The short answers
The questions first-time buyers ask most, answered plainly. The detail is further down the page.
Many can, usually starting with a condo or a townhome rather than a house. North Vancouver has a large supply of condos, including many priced under $835,000, where the BC first-time buyer Property Transfer Tax exemption can still save a qualifying buyer up to $8,000. Your budget depends on your income, debts, down payment and the mortgage stress test, so a pre-approval is the real first step.
Five main programs: the First Home Savings Account, the RRSP Home Buyers' Plan, the BC first-time buyer Property Transfer Tax exemption, the federal GST rebate on new homes, and the federal Home Buyers' Amount tax credit. First-time buyers can also choose a 30-year insured mortgage. Most people qualify for more than one.
At least 5% of the first $500,000 and 10% of the portion above that, for homes under $1.5 million. On a $750,000 condo that is $50,000. With less than 20% down you also pay mortgage default insurance, which is usually added to your mortgage.
Often only part of it. If you qualify, the first $500,000 of the price is exempt for homes worth up to $835,000, which saves up to $8,000. A partial exemption applies up to $860,000. Above that, the first-time exemption does not apply, though a brand new home may qualify for a separate newly built home exemption.
Yes. First-time buyers can get back up to $50,000 of GST on a new home bought from a builder. The full rebate applies to homes under $1 million and phases out by $1.5 million. The purchase agreement must be signed on or after March 20, 2025, and the home must be your primary residence.
Usually in condo-rich areas: Lower and Central Lonsdale for walkability and the SeaBus, Lynn Valley and Lynnmour for trails and a quieter pace, and Roche Point for the waterfront. First-time buyers with a bigger budget often look at townhomes in Lynnmour and Mosquito Creek.

The rules for each program are different, including the definition of a first-time buyer. Check each one separately.
Save up to $8,000 a year, to a lifetime maximum of $40,000. Contributions are tax-deductible, growth is tax-free, and qualifying withdrawals for your first home are tax-free. Unused room carries forward, up to $8,000 a year. Open one as early as you can, because room only starts building once the account exists. A couple can save up to $80,000 between them.
Withdraw up to $60,000 from your RRSP for a first home, tax-free, and repay it over 15 years. You can use it together with an FHSA.
For qualifying first-time buyers, the first $500,000 is exempt on homes worth up to $835,000, with a partial exemption up to $860,000. You must be a Canadian citizen or permanent resident, have lived in BC for a year (or filed two BC tax returns in the last six years), never have owned a principal residence anywhere, move in within 92 days and live there for a year.
A separate BC exemption for brand new homes that will be your principal residence. It is full up to $1,100,000 and partial up to $1,150,000, and you do not need to be a first-time buyer. For a new home, it is often the better of the two.
Up to $50,000 of GST back on a new home from a builder, including presale condos. Full under $1 million, phasing out by $1.5 million. You must be 18 or older, a citizen or permanent resident, the first person to live in the home, and not have lived in a home you or your spouse owned in the current year or the previous four.
First-time buyers can choose a 30-year amortization on an insured mortgage, which lowers the monthly payment. Insured mortgages are available on homes up to $1.5 million. At tax time, the federal Home Buyers' Amount gives a $10,000 credit, worth up to $1,500.
Simple examples for first-time buyers who qualify for each program. Your numbers will differ.
A $750,000 resale condo.
Minimum down payment: $50,000 (5% of $500,000 plus 10% of $250,000).
Property Transfer Tax without the exemption: $13,000. With the first-time buyer exemption: $5,000. That is a saving of $8,000.
The $50,000 could come from one person's FHSA ($40,000) plus $10,000 from an RRSP through the Home Buyers' Plan.
A $900,000 brand new condo from a builder.
GST at 5% would be $45,000. With the first-time buyer GST rebate, a qualifying buyer could get all of it back.
The first-time buyer Property Transfer Tax exemption does not apply at this price, but the newly built home exemption does. Property Transfer Tax: $0.
That is up to $45,000 in GST and $16,000 in Property Transfer Tax that a qualifying first-time buyer would not pay.
Examples are simplified and assume the buyer qualifies for every program shown. Rules change, and eligibility depends on your situation. This is not tax, legal or mortgage advice. Confirm the details with your mortgage broker, lawyer or notary, and accountant.
The path
Most of the work happens before you ever see a home. Doing it in this order saves time, money and stress.
01
Contribution room only starts building once the account is open. Opening it a year or two early can be worth thousands in tax savings.
02
A mortgage broker checks your income, debts and credit and runs the stress test. You have to qualify at the higher of your contract rate plus 2% or 5.25%. The result is your real budget, not a guess.
03
Budget for the down payment, any Property Transfer Tax, legal or notary fees, an inspection, property tax and strata fee adjustments, moving and insurance. The deposit, often 5% for a resale home, is usually due within a day or two of your offer becoming firm.
04
Decide what matters most: walkability, commute, trails, space or schools. Then choose between condo, townhome and new construction. We set up a search that sends you matching listings the day they come out.
05
Most first-time buyer offers include subjects for financing, an inspection and a review of strata documents. In BC you also have a three business day rescission period after acceptance, with a fee of 0.25% of the price if you use it.
06
Your lawyer or notary handles the paperwork and the transfer, and claims any Property Transfer Tax exemption. After you move in, claim your Home Owner Grant and the Home Buyers' Amount at tax time.
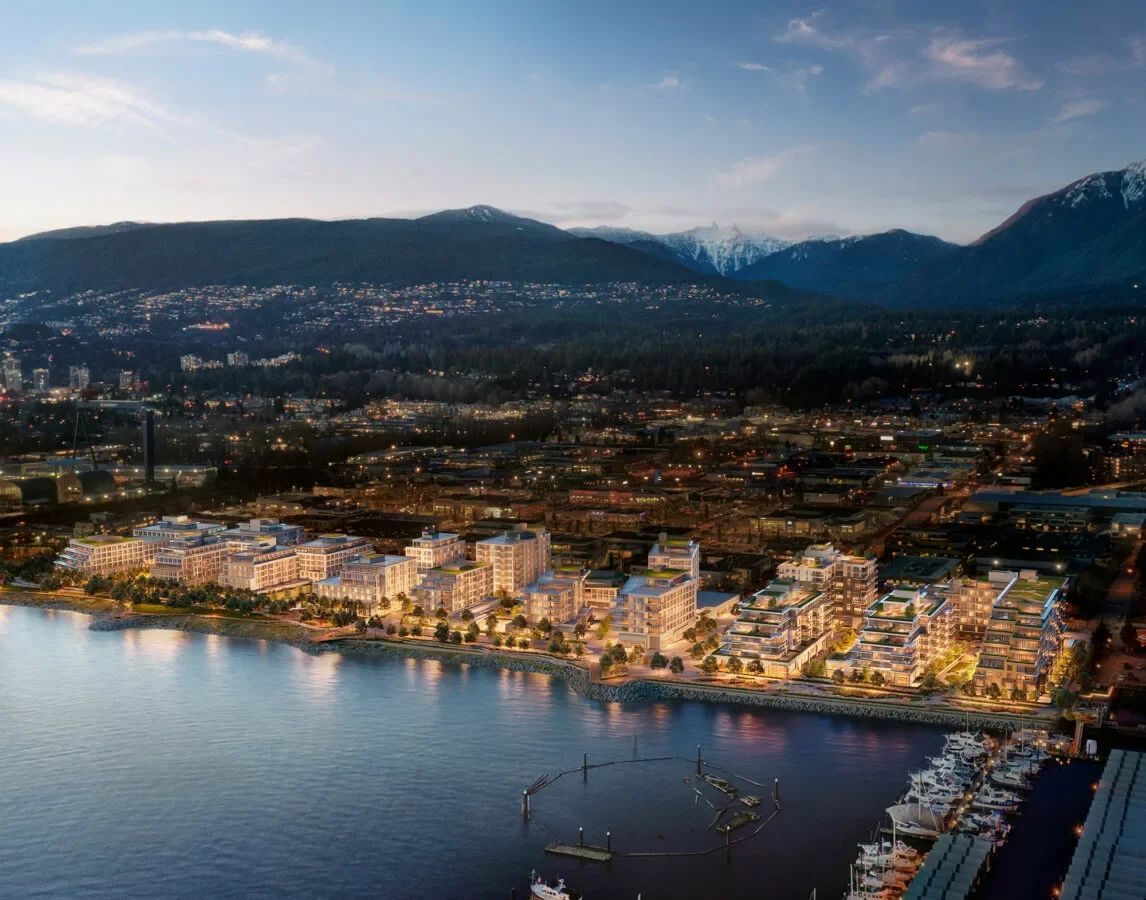
Resale condo. The most affordable way into North Vancouver, often priced where the first-time buyer Property Transfer Tax exemption applies in full (up to $500,000) or in part. Check the strata documents carefully, especially in older buildings.
Townhome. More space, a private entry and often a garage, with the exterior looked after by the strata. Prices are higher, so the first-time buyer exemption often does not apply.
Presale or brand new. This is where the first-time buyer GST rebate and the newly built home exemption can save the most. The trade-offs are waiting for completion, larger deposits spread out over time, and a mortgage approval that has to hold up when the building is finished. See our North Vancouver presales and new homes guide.
Each link shows condos currently listed under $835,000, where qualifying first-time buyers save up to $8,000 on Property Transfer Tax.
Looking at townhomes instead? Start with Lynnmour, Mosquito Creek and Central Lonsdale, all under $1.3 million. Browse all North Vancouver condos or townhomes.
Shopping before pre-approval. It is easy to fall for a home you cannot finance. Get the number first.
Forgetting the cash to close. The down payment is not the only cheque. Property Transfer Tax, legal fees and adjustments are due on completion and cannot usually be added to the mortgage.
Skimming the strata documents. Minutes, the depreciation report and the contingency fund tell you about upcoming special levies. Read them before subjects come off.
Changing your finances mid-purchase. A new car loan, a job change or a big credit card balance before completion can put your mortgage approval at risk.
Opening the FHSA too late. Room only builds once it is open, so start now even if buying is a few years away.
Assuming you qualify. Each program has its own definition of a first-time buyer. A partner who has owned before, or time spent owning a home abroad, can change what applies.

More questions
Yes. You can withdraw from both for the same home, which is how many first-time buyers build a larger down payment. Each has its own rules and timing, so plan your withdrawals with your bank or financial advisor before you make an offer.
It depends on the program. The BC Property Transfer Tax exemption looks at each buyer, and the exemption can be reduced when one buyer does not qualify. The GST rebate and the FHSA look at whether you lived in a home that you or your spouse or partner owned recently. Have your lawyer or notary and your accountant confirm before you buy.
Plan for any Property Transfer Tax that applies, legal or notary fees, a home inspection, title insurance, property tax and strata fee adjustments, home insurance and moving. These are paid in cash on completion, on top of your down payment. We include an estimate in your first-home plan.
Yes. For most residential purchases, buyers have three business days after their offer is accepted to cancel. Cancelling costs 0.25% of the purchase price, paid to the seller. The rescission period cannot be waived, and it does not apply to some sales, such as court-ordered sales and leasehold properties.
It can be a smart move because of the GST rebate and the newly built home exemption. The trade-offs are a wait of one to several years, deposits paid over time, and the risk that your finances or the market change before completion. A presale contract and disclosure statement are worth reviewing with your lawyer before you sign.
Often, yes. Many lenders accept a gifted down payment from immediate family with a signed gift letter showing that the money does not have to be repaid. Lender rules vary, so tell your mortgage broker early.
Your first-home plan
Tell us where you are at. We will send back the programs you likely qualify for, a realistic price range and the neighbourhoods worth a look.

Your first home
We were born and raised on the North Shore. Scott and Carson started out as development analysts, so every plan starts with honest numbers. Talk to us whenever you are ready, even if buying is a year or two away.
Prefer to call?
Wallace Green Real Estate Group members have assisted 500+ buyers and sellers since 2015. Scott Wallace and Carson Green have both earned Greater Vancouver REALTORS® Medallion Club recognition, an annual award given to the top 10 percent of REALTORS® by units sold across Greater Vancouver. Our brokerage, Oakwyn Realty, ranked #1 on the North Shore by total units sold in 2025, and our North Vancouver office has been the #1 Oakwyn Realty office in Greater Vancouver by gross dollar volume from 2019 to 2025.
500+ buyers and sellers assisted by Wallace Green Real Estate Group members since 2015. North Shore brokerage ranking based on GVR MLS® statistics, January to December 2025. Oakwyn office ranking covers 2019 to 2025, per GVR MLS® statistics. Information on this page is general and is not legal, tax, mortgage or financial advice.